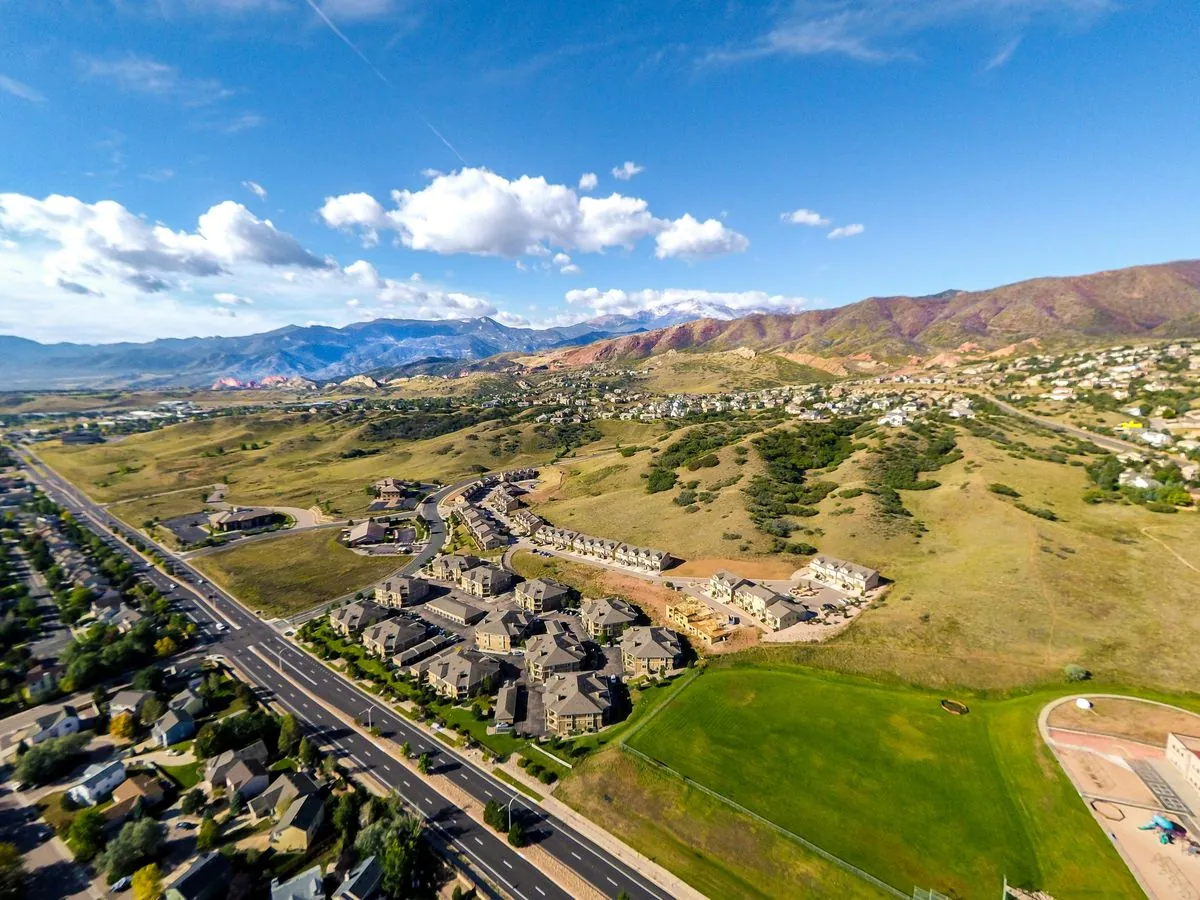
Would you rather buy a new-construction home in a brand new community with a 4% mortgage rate, or an older home in an established community with a 7% mortgage rate?
I asked this question on my Instagram and Facebook pages this week and received split answers.
On the surface that question seems ridiculous. Who wouldn't take a 4% rate? However, it's worth breaking down these options further. There are many other factors to consider when buying a home. It's not just the rate and the price. It's the location, the daily commute, the neighborhood amenities, the style of home and future resale value.
When you buy a new-construction home, you're typically buying at the top of the market in terms of purchase price. However, you can still get a more affordable payment because the builders are offering lending incentives all the way down to 3.99% for a 30-year fixed. In a time when the 30-year average mortgage rate just hit 7.5% this week, the highest it's been in 2 years, that 3.99% sounds mighty appealing.
I helped two clients secure a contract on a new-construction home last weekend. They wanted a more updated home and there weren't many options in the resale market for their budget. Enter the new-construction home. They were able to secure a rate of 3.99% over 30 years. That promotion ended just one day later, not surprisingly.
How are builders able to offer those rates?
When a company like Lennar, Richmond, Toll Brothers, Meritage or any other large residential home-builder builds out a community of homes, they purchase the land and then factor in the "cost of goods sold" into their equation. They have their own mortgage and title departments under the same holding company. They have a certain amount of money to play with in buying down the mortgage rate because they know before building the house that they might need to offer those incentives. It's a whole structure. They also have multiple banks who will purchase their loans at a discounted price because of the volume of loans they're issuing.
So when a builder is offering these kinds of incentives, it's telling of the kind of demand they're seeing. They need to get these homes off the books because the market is slow and they just built a whole new community of supply. They charge market price, which is still relatively high. However, they're able to create affordability by buying down the rate.
This is an interesting solution for today's first-time home buyer who wants an updated home at an accessible monthly payment.
So, what's the catch?
When evaluating real estate from an investment standpoint, you need to consider your entry price (buy), your maintenance, taxes, insurance and interest costs while holding the home, and then your exit price (sale).
With new-build homes, you enter at a higher price for the current market. Your maintenance costs should be low considering it's brand new. However, your taxes are usually higher than homes in established communities because they use metro district taxing to pay back the builder and city over time for building out all of the roads and utilities in that newer community. The interest cost is lower. The exit price is where it really gets tricky.
You must know that you're buying into an area with increased supply and low demand at the "top of the market" price. Your payment might be great, but if something happens and you have to turn around and sell that house in the coming 5 years, chances are you will be selling it for less than what you bought it for. That's because you're selling in an area with an increased supply of homes that are very similar to yours. Additionally, the same builder you bought from might still be selling in or around that area, using the same lending incentives they lured you in with. Now you're a traditional resale home seller competing with that builder, and you can't offer that same lending incentive because you don't have an in-house mortgage company like they do. So your only option is to go down in price to sell.
Therefore, you have to be cautious when buying into a new community. You need to analyze how large the community will be, what the future competing supply will look like if you have to sell, and what the future demand could be in that area.
So the advice I gave to my clients last weekend, and to anyone wanting to buy a new-construction home, is to hold onto the property for as long as you can — ideally at least 7–10 years. Unless you're playing the fix & flip game, that's the case for most real estate. It's a long game. With new construction, it has to be viewed as an even longer hold in order to see any return at resale.
What about the rate difference, though?
It's fully worth exploring the difference in interest payments over the same period of time.
Let's assume you buy a $600,000 home in an established neighborhood that doesn't have as much supply, versus a $600,000 new-build home in a new neighborhood.
- You put 10% down on both homes.
- Your tax payment is $2,000/year more on the new-build home.
- Your insurance is $1,000 less on the new-build home.
- Your rate is 4% on the new build and 7% on the established home.
You'd be paying a total of $183,869 of interest alone in the first 5 years on the 7% mortgage. You'd be paying a total of $103,099 of interest in the first 5 years on the 4% mortgage.
That $80,770 difference is roughly 13% of the initial purchase price. Therefore, you need to consider whether the new-build home or the established home would yield that much of a valuation difference in 5 years. At that point, it all comes down to location and the future supply and demand in the area. This also assumes that rates don't come down in the next 5 years so the 7% buyer can refinance. There's no telling where rates will be in 5 years, so it's never a bad idea to lock in a lower rate — as long as you're willing to hold that real estate long term.
Latest video
This week's video covers why people are still moving to Denver despite the headlines saying otherwise. Watch it on YouTube →